
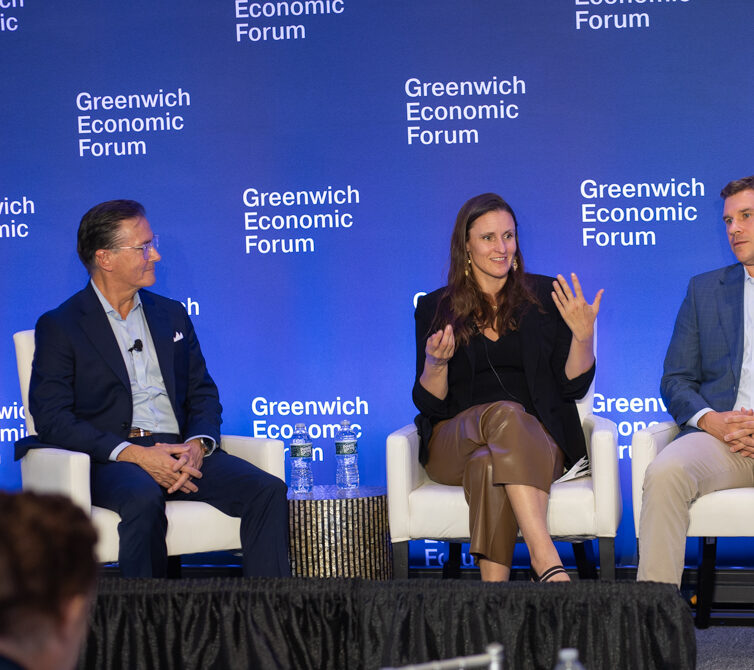
PitchBook: Liquidity, private credit and the regulatory environment keep LPs up at night
Liquidity, valuations and private credit were key themes at the Greenwich Economic Forum, an annual gathering of alternative investors that took place in Greenwich, CT., from 5-7 October.
. . .
Late last year, NEPC adjusted its pacing model to reflect this longer hold period. The firm extended its fund life assumption for VC vehicles to 17 years. Other assumptions include 15 years for buyout, 16 years for fund-of-funds and eight years for private debt.
Without these adjustments, actual fund lives and net asset values extend beyond the model’s assumptions and reduce LPs’ capacity to commit to future funds, said Sarah Samuels, the investment consultant’s chief investment officer.
“Don’t try to time vintage years, and don’t skip funds. If you do need to pull back, pull back in check size. Don’t skip a high-conviction GP,” she said.
. . .

Pensions & Investments: Endowments scored big on SpaceX, creating a potential risk management problem for universities
U.S. college and university endowments are beginning to post their returns for the fiscal year ended June 30, with at least two citing their investments in SpaceX as a major driver of outperformance, but experts warn the high concentration of their portfolios in a single stock creates asset allocation and risk problems.
. . .
Colin Hatton, principal and senior consultant for endowments and foundations at NEPC, said concentration risk becomes more acute as a holding grows. One of the clearest warning signs for investment committees is when a single company reaches roughly 5% of total assets, he said.
Such concentrations are uncommon in modern endowment portfolios, which generally rely on diversification to generate steadier returns and support annual spending, he said. Still, large single-company positions are not unprecedented: Some institutions with sizable venture portfolios are approaching 5% exposure to individual companies, and a smaller number have exceeded that level.
. . .
Structured Credit Investor: Rated feeder boom driven by insurers, says NEPC
Rated note feeder structures continue to gain traction across private markets, as institutional investors seek more efficient ways to allocate capital while managing regulatory constraints.
. . .
“Rated note feeder structures can improve capital treatment by allowing a portion of a private market investment to be held on Schedule D rather than Schedule BA,” Colton Lavin, principal and senior investment director in private debt at NEPC tells SCI. “As a result, we have observed some investors, particularly insurance companies, view these structures as a potential tool for expanding private market allocations while managing associated capital charges.”
. . .
Despite the growth in issuance, NEPC cautions that rated note feeders should not be the primary driver of allocation decisions. Instead, investors should first assess the underlying private market strategy before considering whether a rated feeder structure adds incremental value.
“We believe rated note feeders should generally be viewed as a secondary consideration rather than a prerequisite,” Lavin adds.
. . .
Click here to continue reading the full Structured Credit Investor article.
Family Office Exchange (FOX): Aligning the Investment Function and Mandate With the Family's Needs With Karen Harding and Stacey Flier
Karen and Stacey share their perspectives on how the investment needs, preferences, and expectations of families and family offices have evolved over the years. Drawing on decades of experience advising ultra-high-net-worth families, they discuss the growing complexity of the investment function and the increasingly sophisticated approaches families are taking to achieve their objectives.
. . .
“I think what’s really interesting is that the decision isn’t really a decision about outsourcing the decision-making. It’s really a decision about how you partner together. Most OCIO relationships, at least the best ones, are actually really collaborative. The family is still in control.”
. . .
“Not only is the investment environment dynamic and changing, but families are dynamic and changing. And we want to be there partnering with our families through that process.”
. . .
“The family is still in control. They are the ones who are setting the objectives, the goals, the priorities, the overall direction—all of those things. But their OCIO partner is helping them execute the day-to-day parts of the strategy. They’re providing the resources and bringing those best practices to the table to help them meet their goals.”
. . .
Click here to listen to the full podcast epsiode from Family Office Exchange.
Pensions & Investments: DOL’s alts proposal could accelerate the shift to 3(38) fiduciaries in DC plans
Plan sponsors increasingly want advisers to play a bigger role in investment decisions, and the recent Department of Labor proposal on investment alternatives in defined contribution plans could further fuel that appetite.
. . .
Aaron Chastain, partner and corporate solutions leader at NEPC, said the firm’s corporate-client discretionary assets have increased about 4.5 times over the last five years.
. . .
Chastain said he expects some sponsors to keep a 3(21) adviser for most of the plan, while handing off manager selection or operations for a specific sleeve — such as alternatives — to a 3(38) manager.”
“Using an external party or outsourcing doesn’t have to be an all-or-nothing type approach,” Chastain said.
Institutional Investor: Overseas Stocks Drive Double-Digit Returns for State Plans Like Louisiana and New York
Several state pensions have benefited from the surge in non-U.S. equities, including emerging markets.
. . .
According to NEPC’s head of marketable equity research Nedelina Petkova, strong performance from financials, industrials, and defense-related businesses and ongoing improvements in Japan have helped international developed markets. Plus, Petkova wrote that EAFE (Europe, Australasia, and the Far East) performance “has been less dependent on a small number of technology companies and reflects a broader set of economic drivers than the U.S. market.”
. . .
Bloomberg: Cash-Strapped Colleges Are Draining Their Endowments to Survive
Like borrowing from a 401(k), the tactic can help short-term but carries big long-range risks.
. . .
“Once you get much over a spending rate of 7%, consistently, you are an at-risk endowment,” said Kristin Reynolds, who advises endowment administrators on their investment strategies at consulting firm NEPC. She was speaking generally, not about a specific college.
. . .
Pensions & Investments: Why active equities dominated 401(k) plan fund changes in 2025
The ongoing challenges of active management were reflected in 401(k) plan fund changes in 2025, as concentration in large-cap equities and poor performing quality small-cap equities forced some plan sponsors to replace funds, according to defined contribution plan consultants.
. . .
Mikaylee O’Connor, partner and head of defined contribution solutions at NEPC, said among their clients, active growth funds have faced more challenges than active value funds, because of the hurdles of the extreme concentration of the growth index with the dominance of tech stocks.
“(Retirement plan) committees really have responded in different ways. I will say some have moved to passive large-cap growth while retaining active largecap value, and I think that’s a recognition that this has been one of the top performing asset classes, and so they’re reevaluating how (to) actually deliver that to participants,” O’Connor said.
Others, she said, have moved to eliminating any style-specific large-cap funds and simply moved to a passive core allocation.
“I think the main theme there is that committees are revisiting their menu structures. We actually did a little bit more digging into this, and in the last five years, approximately 30% of our clients have made structural changes to their large-cap lineup,” such as swapping out active managers, she said.
“So it’s not just in the last year, but over the last five years, we’ve seen this trend of making some sort of (large-cap) change.”
. . .
Pensions & Investments: DC retirement plan assets drive explosive OCIO growth, and experts say it’s just the beginning
Fewer fiduciary risks, greater access to private markets investments, improved corporate governance and lower costs are among the reasons retirement plan sponsors choose outsourced chief investment officer services, producing an asset surge under OCIO management plus predictions that there’s more to come.
. . .
Fiduciary risk is a “commonly cited reason” when DC sponsors consider OCIO services, said Aaron Chastain, partner and corporate solutions leader for the NEPC consulting firm.
Hiring OCIO services doesn’t eliminate fiduciary risk because sponsors have a fiduciary duty to monitor OCIO activities, and sponsors’ ERISA lawyers are “very involved” in making sure sponsors understand their responsibilities, he added
. . .
For many sponsors, OCIO is “a more efficient way to access alternatives investments,” Chastain said. “It allows sponsors to focus on policy decisions” about which — if any — private markets investment they want to offer. OCIO handles the manager selections, he said.
. . .
“Employers first embraced OCIOs to outsource investment oversight, and PEPs are emerging as the next evolution, enabling them to offload much of the administrative burden of running a retirement plan,” Chastain said. “It allows organizations to focus on their core business while retirement plan experts handle the rest.”
. . .
With Intelligence: The Alts 50 List
NEPC Partner and Chief Investment Officer Sarah Samuels, CFA, CAIA, has been named to With Intelligence’s inaugural Alts 50, recognizing the 50 most influential institutional allocators across the alternatives industry. Read the full With Intelligence announcement to learn more about the Alts 50 and this year’s distinguished honorees.
The Alts 50 highlights institutional investors at the forefront of alternatives, recognizing allocators who are driving innovation, influencing capital allocation, and helping shape the evolution of private markets. The inaugural list brings together leaders from across the institutional investment landscape whose expertise and leadership continue to have a meaningful impact on the industry. The inaugural ranking celebrates leaders whose investment decisions, strategic vision, and industry influence are shaping the future of alternative investing. The Top 10 honorees will be revealed live at the Alts 50 Awards Dinner in New York on October 27.
. . .
Sarah Samuels, Chief Investment Officer at NEPC, was recognized among this inaugural group of influential institutional allocators for her leadership and contributions to the alternatives investment community.